
The Commodity Futures Trading Commission has taken a significant step toward clarifying the regulatory boundary between traditional sports betting and federally supervised prediction markets. On October 19, 2026, a new federal rule took effect excluding qualifying casino-style gambling products, including conventional sportsbook wagers, from the legal definition of a swap under the Commodity Exchange Act.
The decision comes as sports prediction markets operated by companies such as Kalshi face legal disputes over whether contracts linked to sporting events should fall under federal derivatives regulation or state gambling laws.
The CFTC’s action does not eliminate those disputes. Instead, it establishes a clearer distinction between two products that can produce similar financial outcomes but operate through different legal and commercial structures.
Under the interim final rule, qualifying wagers offered by state-licensed or tribally authorized gambling businesses remain outside the CFTC’s swap jurisdiction. Separately, the commission has proposed explicitly including event contracts, including those based on sports, politics, culture and weather, within the swap definition.
The distinction is essential: the casino-style gambling exclusion is already effective, while the separate event-contract inclusion proposal has not been finalized.
Both documents appeared in the Federal Register on October 19, with public comments due November 18, 2026.
The CFTC’s official interim final rule explains why the agency considers conventional gambling products different from derivatives traded on federally regulated exchanges.
For sportsbooks, prediction-market platforms, state regulators and consumers, the development provides a new reference point in one of the most consequential U.S. gambling-regulation debates of 2026.
CFTC Excludes Traditional Sportsbook Wagers From The Swap Definition
The Commodity Futures Trading Commission announced its interim final rule on October 9, 2026, before the measure became effective through publication in the Federal Register on October 19.
The rule is titled Further Definition of “Swap” to Exclude Casino-Style Gambling Products and carries regulatory identification number RIN 3038-AF81.
CFTC Chairman Michael S. Selig described the action as a clarification of the agency’s existing position that conventional casino-style gambling products are not derivatives.
The rule addresses an important legal question.
If a contract produces a payment based on the outcome of a sporting event, does that automatically make it a financial derivative regulated by the CFTC?
The commission’s answer is no.
The economic outcome alone does not determine the legal classification.
A wager accepted by a licensed sportsbook and a sports event contract traded on a derivatives exchange may both depend on whether a team wins. However, the way the products are offered, priced, executed and regulated can differ substantially.
The interim final rule adds an exclusion to the federal regulatory definition of a swap, confirming that certain gambling transactions remain outside that category.
The measure covers qualifying sports wagers, casino games and other licensed games of chance.
It does not create a nationwide authorization for sports betting, remove state gambling restrictions or automatically legalize products offered by unlicensed businesses.
Instead, it clarifies the scope of federal derivatives oversight.
Why The October 19 Rule Matters For U.S. Sports Betting
Sports betting in the United States operates through a regulatory system that differs significantly from financial derivatives markets.
Following the Supreme Court’s 2018 decision in Murphy v. National Collegiate Athletic Association, individual states gained the ability to authorize and regulate sports wagering without the former federal prohibition imposed by the Professional and Amateur Sports Protection Act.
Since then, states have developed different licensing, taxation, consumer-protection and market-approval requirements.
For example, New Jersey regulates licensed sports wagering through its Division of Gaming Enforcement and other applicable state authorities.
Pennsylvania regulates its authorized sports betting operations through the Pennsylvania Gaming Control Board.
Michigan operates its own licensing and oversight framework through the Michigan Gaming Control Board.
Tribal gaming also involves distinct legal arrangements, including federally recognized tribal authority and applicable federal and tribal gaming laws.
The CFTC’s new rule recognizes this established regulatory landscape.
It does not transfer conventional sportsbook oversight from states and tribes to federal derivatives regulators.
Instead, it establishes a legal exclusion intended to prevent ordinary licensed gambling products from being classified as swaps merely because they depend on uncertain future outcomes.
That distinction matters for businesses operating across multiple jurisdictions.
A sportsbook offering conventional moneyline, spread or totals wagers must comply with the gambling laws applicable to its operations.
The existence of a federally regulated event-contract market does not replace those requirements.
Two Tests Determine Whether A Gambling Product Qualifies For The Exclusion
The October 19 interim final rule establishes two principal conditions for the new exclusion.
The CFTC refers to these as the Provider Test and the Product Test.
Both are important because the rule does not simply exclude every transaction that resembles gambling.
| Regulatory Test | Principal Requirement | Practical Significance |
|---|---|---|
| Provider Test | The product must be offered by a properly licensed or authorized state or tribal gambling provider acting within its authorization, and regulated as gambling under applicable law. | Connects the exclusion to established gambling oversight. |
| Product Test | The transaction must not be traded on an exchange or other multilateral trading market, or executed through individual negotiation of the type described in the rule. | Distinguishes conventional house-based wagers from tradable financial contracts. |
The Provider Test focuses on the legal status of the business offering the product.
A sportsbook licensed by an applicable state gaming regulator may satisfy this requirement when acting within the scope of its authorization.
The Product Test focuses on how the transaction operates.
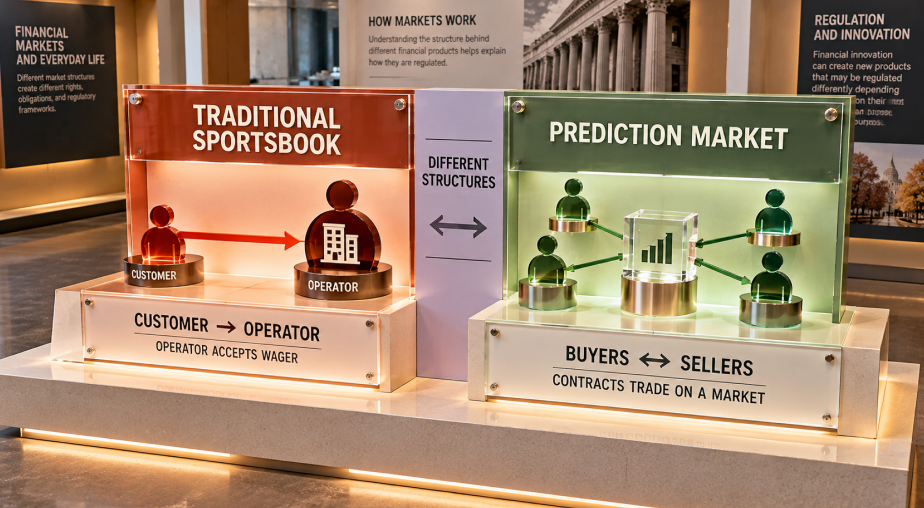
Traditional sportsbook wagers generally involve a customer accepting terms offered by the sportsbook. The operator acts as the counterparty, and the wager is governed by established house rules.
By contrast, exchange-traded event contracts may involve buyers and sellers interacting through a market structure in which prices reflect bids and offers.
These structural differences are central to the CFTC’s reasoning.
Importantly, failing to satisfy the exclusion does not automatically establish that a transaction is a swap.
The commission expressly recognizes that other transactions may require separate legal analysis.
The Federal Register’s October 19 rulemaking text provides the full regulatory language and explanation of both tests.
How Sportsbook Bets Differ From Prediction-Market Contracts
The most useful way to understand the new distinction is to compare how a conventional sportsbook wager operates with an exchange-traded event contract.
Consider a hypothetical professional football game between two teams.
A licensed sportsbook might offer a moneyline wager on Team A at decimal odds of 2.00.
A customer accepting those odds would risk a $100 stake for a potential $200 total return if the wager wins, including the original stake.
The sportsbook establishes the offered price and accepts the wager under its rules.
A prediction market could instead list a hypothetical binary contract that pays $1 if Team A wins and $0 if the specified outcome does not occur.
If the contract trades at $0.50, a purchaser pays $0.50 for a contract that could settle at $1.
Both products provide exposure to the same sporting result, but their commercial structures are different.
The sportsbook wager is offered by a gambling operator acting as the counterparty.
The exchange-traded contract may be bought or sold through an order book, with prices determined by market participants.
The event contract may also be transferable before settlement, depending on the market’s rules.
This tradability is one of the characteristics the CFTC considers relevant when distinguishing derivatives from conventional gambling products.
The hypothetical prices above are educational examples, not actual sportsbook odds or live prediction-market quotations.
For background on how traditional sports betting markets define outcomes and pricing, our guide to the 1X2 betting market explains the structure of three-way soccer wagers.
CFTC Separately Proposes Including Event Contracts As Swaps
The gambling exclusion was not the only significant CFTC action published on October 19.
A separate proposed rule, titled Further Definition of “Swap”—Inclusions, would explicitly clarify that certain event contracts fall within the Commodity Exchange Act’s definition of a swap.
The proposal carries regulatory identification number RIN 3038-AF82.
It addresses contracts based on events involving sports, politics, culture and weather.
Unlike the casino-style gambling exclusion, this measure is a proposed rule rather than an effective final regulation.
The CFTC is seeking public comments before determining whether to adopt the proposal and whether its language should be modified.
The commission’s reasoning centers on the Commodity Exchange Act’s broad definition of swaps, which includes certain transactions dependent on events associated with potential financial, economic or commercial consequences.
Sports outcomes can have such consequences.
Professional games influence broadcasting agreements, sponsorship arrangements, team finances, advertising activity and other commercial relationships.
The CFTC argues that this connection can support the classification of exchange-traded sports event contracts as swaps.
However, that reasoning remains contested in federal litigation.
The CFTC’s October 19 event-contract proposal sets out the agency’s interpretation and invites comments on its legal and practical implications.
The simultaneous publication of the two measures is particularly important.
The commission is attempting to establish a clearer boundary between conventional gambling products and federally regulated event contracts without treating every transaction linked to a sporting result as legally identical.
Kalshi And The Federal Courts Remain Central To The Debate
Kalshi has become one of the most prominent companies in the legal dispute surrounding sports prediction markets.
The company’s event-contract model operates through federally regulated market infrastructure, distinguishing its commercial structure from that of a conventional state-licensed sportsbook.
However, state regulators have questioned whether sports event contracts function as gambling products that should be subject to state licensing and consumer-protection requirements.
The resulting litigation has produced different interpretations of federal law.
One important case is KalshiEX LLC v. Flaherty, decided by the United States Court of Appeals for the Third Circuit in 2026.
The court concluded that sports-related event contracts traded on a CFTC-licensed designated contract market could fall within the Commodity Exchange Act’s swap definition.
The decision supported the view that the economic consequences associated with sporting events can satisfy the statutory language.
Other courts have reached different conclusions or expressed concerns about the boundaries between federal derivatives jurisdiction and state gambling authority.
The October 19 rulemaking documents acknowledge those conflicting interpretations.
The commission’s response is to distinguish the legal structure of exchange-traded event contracts from conventional sportsbook transactions.
This approach may influence future legal arguments, but an agency rule does not automatically eliminate all pending litigation.
Courts may still need to address statutory interpretation, federal preemption, the application of gambling laws and the legal status of particular products.
The disputes are therefore unlikely to disappear solely because the CFTC has clarified its regulatory position.
What The Rule Means For DraftKings, FanDuel And State-Licensed Sportsbooks
For conventional sportsbook businesses, the most immediate significance is regulatory clarity.
Companies such as DraftKings and FanDuel operate licensed sportsbook businesses in jurisdictions where sports wagering is authorized.
Their conventional state-regulated sportsbook wagers are not transformed into federally regulated swaps merely because those wagers depend on the outcome of sporting events.
The interim final rule reinforces that distinction.
However, the exclusion applies to qualifying products and providers rather than granting a blanket exemption to every activity conducted by a gambling company.
If a business also participates in derivatives markets or offers a different type of financial contract, the legal classification of that activity requires separate analysis.
This distinction is increasingly relevant as gambling companies, financial technology platforms and prediction-market operators explore overlapping products.
A business may operate in more than one regulated market, but its corporate identity alone does not determine the legal status of every transaction it offers.
The applicable product structure, regulatory authorization and execution method remain important.
The rule also does not change state sportsbook licensing requirements, gambling taxes, minimum-age restrictions or responsible-gambling obligations.
The CFTC’s October 9 announcement presents the exclusion as a clarification of existing federal jurisdiction rather than a new federal sportsbook licensing system.
What The Changes Mean For Consumers
For consumers, the distinction between sportsbooks and prediction markets remains important even when two products reference the same sporting event.
A traditional sportsbook customer generally enters into a wager with an operator under the gambling rules applicable to that jurisdiction.
An event-contract participant may instead trade a contract through a federally regulated exchange and associated intermediaries.
The two arrangements can differ in their pricing, settlement, transaction fees, market liquidity and applicable customer protections.
They can also involve different dispute-resolution procedures.
A sportsbook may offer a fixed price when a wager is accepted, while an exchange-traded event contract may change in price as other participants submit bids and offers.
Neither structure guarantees favorable financial outcomes.
Customers should also distinguish between the probability implied by a contract’s trading price and the actual likelihood of the event occurring.
A binary contract trading at $0.60 may be interpreted as reflecting a market-implied probability of approximately 60%, before considering fees and other market factors.
That figure is not an objective guarantee that the event has a 60% chance of occurring.
Likewise, sportsbook odds incorporate pricing decisions and operator margins.
Understanding these differences is more useful than assuming that one type of product is inherently safer or more advantageous than another.
The CFTC’s clarification also should not be interpreted as permission to access gambling products in jurisdictions where they are prohibited.
Consumers must consider the rules applicable to their location and the legal status of the specific platform.
State And Tribal Gambling Regulators Retain An Important Role
The interim final rule explicitly recognizes the historical authority of state and tribal gambling regulators.
That recognition matters because U.S. gambling regulation is not organized through a single nationwide licensing system.
States determine which conventional gambling products may be offered under their laws and establish corresponding oversight requirements.
Federally recognized tribes exercise gaming authority within the applicable tribal and federal legal framework.
The Indian Gaming Regulatory Act remains an important part of that system.
The CFTC’s exclusion is structured around these existing regulatory arrangements.
It does not remove the authority of state gaming commissions to investigate unauthorized gambling operations or enforce requirements applicable to licensed sportsbooks.
At the same time, the commission maintains that qualifying exchange-traded event contracts can fall within federal derivatives jurisdiction.
The resulting question is not simply whether sports betting should be regulated.
It is which regulatory framework applies to a particular product and whether federal law limits the application of state gambling requirements.
Those questions are central to ongoing prediction-market litigation.
The October 19 actions provide clearer regulatory definitions, but they do not establish a universal answer for every contract, provider or jurisdiction.
November 18 Comment Deadline Could Shape The Final Regulatory Framework
Both October 19 rulemaking documents establish November 18, 2026, as the deadline for written public comments.
However, their procedural status differs.
The casino-style gambling exclusion is already effective as an interim final rule.
The event-contract inclusion measure remains a proposal.
The CFTC may review comments on the interim final rule and consider amendments. It may also modify or decline to finalize the separate event-contract proposal.
Interested parties can submit comments through the federal Regulations.gov system using the relevant rulemaking identifiers.
The CFTC’s public-comment instructions explain how to locate rulemakings and submit responses.
Submissions may address the distinction between exchange-traded contracts and conventional gambling wagers, the treatment of different providers and the legal basis for classifying event contracts as swaps.
The commission is also likely to receive competing interpretations of how federal derivatives law interacts with state gambling authority.
These comments could help shape the final regulatory language, although they do not determine the outcome of pending court cases.
What To Watch In The U.S. Sports Betting And Prediction-Market Debate
The October 2026 developments establish an important regulatory milestone, but several questions remain unresolved.
One concerns whether the CFTC will finalize its proposed inclusion of event contracts within the swap definition.
Another concerns how federal courts will interpret the relationship between that definition and state gambling laws.
A third involves the commercial development of sports prediction markets.
As more businesses explore event contracts, regulators may face additional questions about market integrity, consumer protection, trading transparency and the responsibilities of intermediaries.
The distinction between conventional sportsbooks and derivatives exchanges could also become more important as products evolve.
New financial structures may not fit neatly into the categories used by existing gambling and derivatives regulations.
The CFTC’s two-part approach attempts to address that challenge by focusing on the legal and operational characteristics of transactions rather than treating all event-based products as equivalent.
For the U.S. gambling industry, the immediate result is a clearer exclusion for qualifying traditional sportsbook and casino products.
For prediction markets, the more consequential regulatory debate remains active.
The October 19 rule clarifies what conventional casino-style gambling is not under federal derivatives law. The separate event-contract proposal addresses what certain prediction-market contracts may be.
How those two positions interact with future court decisions and state regulatory action will remain one of the defining questions for U.S. sports betting and prediction markets beyond 2026.