
Prediction markets have spent the past two years pushing deeper into American sports. Contracts tied to football, basketball, baseball, hockey and soccer have helped platforms such as Kalshi and Polymarket turn sporting events into one of the most visible applications of event-based trading.
Horse racing has proved much harder to penetrate.
The clearest example arrived around the 152nd Kentucky Derby on May 2, 2026. Despite the Derby’s enormous wagering audience, major prediction platforms did not ultimately offer customers a market on the winner. Polymarket briefly listed a Derby market before removing it and refunding trades after Churchill Downs objected, while Kalshi stayed away from the race.
That restraint stands out because prediction-market companies have been willing to fight regulators over sports contracts elsewhere in the United States.
Horse racing presents a different problem. The sport already operates within a specialized federal wagering framework established by the Interstate Horseracing Act of 1978, alongside a mature pari-mutuel system that distributes wagering revenue among tracks, horsemen, operators and other racing interests.
The conflict resurfaced this month at the Racing and Gaming Conference at Saratoga in Saratoga Springs, New York, where prediction markets faced questions from regulators and gaming stakeholders about how far the new model can expand.
Horse racing is consequently becoming one of the most useful tests of prediction-market limits. The question is no longer simply whether an exchange can create a contract around a sporting result. It is whether that contract can coexist with an established wagering system whose legal and economic architecture was created decades before modern prediction markets existed. (Prediction Market Rules and Market Effects)
The Kentucky Derby Exposed a Major Difference
Few sporting events would appear more attractive to a prediction exchange than the Kentucky Derby.
The race has a simple headline question—Which horse wins?—combined with enormous national attention and an established wagering audience. The 2025 Kentucky Derby generated a record $234.4 million in wagering on the Derby race itself and approximately $349 million across the full Derby Day program.
Yet prediction markets were conspicuously absent in 2026.
As Front Office Sports reported on the Kentucky Derby dispute, Polymarket posted a winner market before removing it after Churchill Downs pushed back. Kalshi also did not offer a Derby market.
Churchill Downs CEO Bill Carstanjen has described horse racing as operating under a different legal paradigm from other American sports.
That distinction centers on the Interstate Horseracing Act.
The Derby therefore produced something unusual in the prediction-market industry. Rather than continuing to offer a sports contract while jurisdictional questions moved through litigation, platforms effectively stayed on the sidelines.
That makes the episode more significant than the absence of one race from an exchange.
It suggests horse racing has legal leverage that many other sports have struggled to establish.
The Interstate Horseracing Act Changes the Starting Point
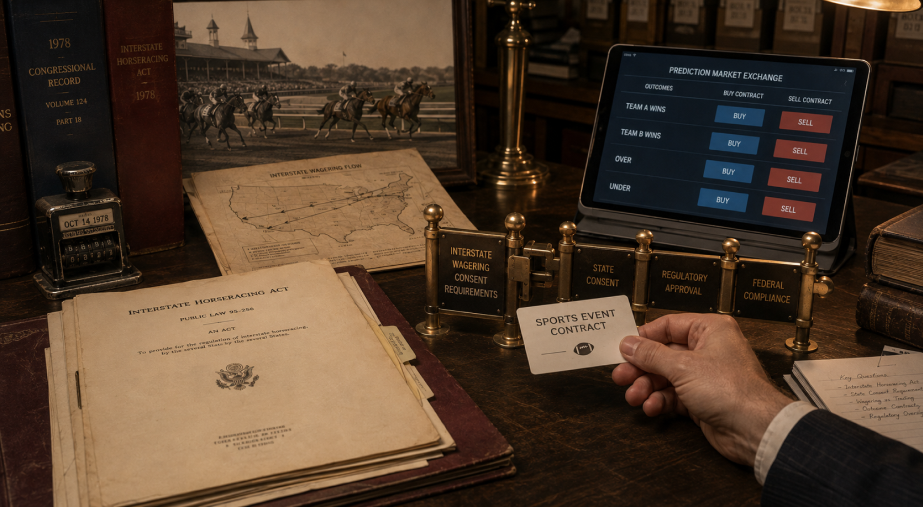
Congress passed the Interstate Horseracing Act in 1978 as interstate and off-track wagering created new conflicts between racing jurisdictions, tracks and wagering operators.
The statute explicitly addresses interstate commerce involving wagering on horse races.
Its policy language also recognizes that states should retain primary responsibility for determining what forms of gambling are permitted within their borders while establishing federal rules for interstate off-track wagering.
Most importantly for today’s prediction-market debate, the law creates consent requirements around qualifying interstate wagers.
The Interstate Horseracing Act therefore gives the racing industry a different starting position from leagues confronting event contracts on ordinary team sports.
Prediction exchanges generally argue that qualifying contracts listed on federally regulated exchanges fall under the Commodity Exchange Act and CFTC jurisdiction.
Horse racing introduces another federal statute into that equation.
The issue is therefore not merely whether federal derivatives regulation preempts state gambling law. It also raises the question of how a modern event contract interacts with federal legislation written specifically to regulate interstate wagering on horse races.
That is a substantially more complicated legal problem.
Racing Already Has a National Wagering Infrastructure
The legal distinction is only part of the challenge.
Horse racing also has an established wagering architecture.
Most U.S. racing bets operate through pari-mutuel pools. Money wagered on the various outcomes is pooled, applicable takeout is deducted and payouts are determined according to how the remaining pool is distributed among winning tickets.
That is fundamentally different from a sportsbook posting fixed odds.
It is also different from a prediction exchange matching buyers and sellers of event contracts.
The distinction matters because pari-mutuel wagering is directly connected to racing’s economic structure.
Tracks, horsemen, advance-deposit wagering companies and state governments can all have financial interests tied to wagering activity.
If an independent prediction exchange creates contracts on the same race without participating in that system, some of the economic activity surrounding the event could occur outside the traditional racing pool.
For racing stakeholders, that creates a much bigger question than whether a contract looks similar to a bet.
It raises the issue of who benefits economically when people trade on the outcome of a race.
Racing Has Consent Leverage Other Sports Often Lack
An NFL franchise generally cannot require every unrelated financial market to obtain permission before creating a contract about whether the team wins.
Horse racing interests argue that their situation is different because of the IHA.
Carstanjen has said the federal framework gives racing organizations rights over wagering on their content and that Churchill Downs has not consented to prediction markets offering wagers on its races.
That position has not yet produced a definitive court ruling establishing how every conceivable prediction contract would interact with the IHA. It should therefore be treated as a consequential legal position rather than an already resolved national precedent.
The practical outcome around the Derby is nevertheless important.
Polymarket withdrew its market.
Kalshi did not offer one.
That contrasts sharply with other prediction-market disputes in which exchanges have continued operating while challenging state regulators.
For an industry built around rapidly expanding the number of tradable events, racing has demonstrated that not every sporting outcome can necessarily be added using the same playbook.
Saratoga Put the Conflict Back in Focus
The debate became timely again during the Racing and Gaming Conference at Saratoga, held August 10–12 at the Saratoga Hilton in Saratoga Springs.
Its agenda included a session titled “Prediction Markets: Innovation, Existential Threat, or Both?”
The conference brought together regulators, racing representatives, attorneys, gaming executives and other stakeholders to discuss changes affecting American gaming.
Prediction markets received significant scrutiny.
Recent coverage of the Saratoga prediction-market debate reported that New York officials and tribal gaming representatives questioned the regulatory treatment of platforms such as Kalshi and Polymarket.
Horse racing was a particularly revealing part of that conversation because prediction exchanges have largely avoided challenging the industry’s existing federal framework.
That is important context.
Saratoga is not merely a convenient conference location. It is one of the most important centers of American thoroughbred racing, and the conference occurred during the Saratoga Race Course meet.
The prediction-market debate was therefore unfolding alongside the industry that may present its toughest sports expansion problem.
Pari-Mutuel Odds and Prediction Prices Work Differently
The pricing question is equally interesting.
Suppose a horse attracts enough money in a pari-mutuel pool to indicate that the public considers it one of the leading contenders.
A prediction exchange could theoretically produce a different implied probability for the same horse.
Neither price would automatically prove the other wrong.
Pari-mutuel odds depend on how wagering money is distributed throughout the pool and how much is removed through takeout.
Prediction-market prices depend on buyers, sellers, market depth, transaction costs and liquidity.
That creates two separate price-discovery mechanisms evaluating exactly the same sporting outcome.
The difference connects directly with our previous analysis of sports prediction-market pricing, which examined why a displayed contract price should not automatically be treated as a perfect estimate of real-world probability.
Horse racing would make the comparison even more complicated.
Racing odds can change dramatically immediately before post time as money enters the pari-mutuel pools. A prediction exchange operating alongside those pools would need to react to the same late information while maintaining enough independent liquidity to produce meaningful prices.
The relationship between those two markets could become one of the most interesting price-discovery experiments in sports.
But first, prediction exchanges need a viable route into racing.
Liquidity Could Become a Bigger Problem Than Regulation
Even if the legal questions were resolved, prediction platforms would encounter another major obstacle: fragmentation.
The Kentucky Derby would probably attract substantial trading interest.
An ordinary Wednesday race at a regional track is a different proposition.
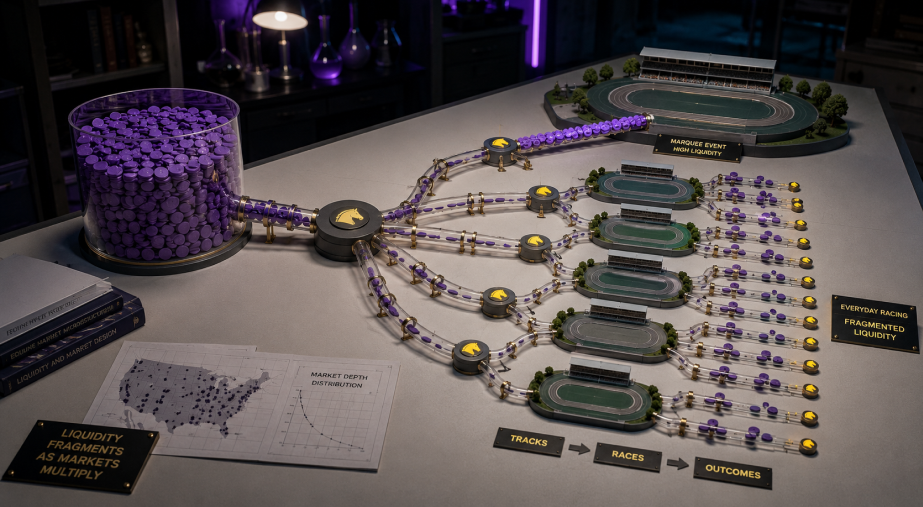
American racing produces thousands of individual races across many venues. A typical card may contain eight, nine or ten races, with multiple horses competing in each.
A prediction exchange trying to replicate that inventory would divide its available liquidity repeatedly.
First by track.
Then by race.
Then by horse.
Consider the difference with an NFL game.
A basic football winner contract involves two teams. A 12-horse race has 12 potential winners.
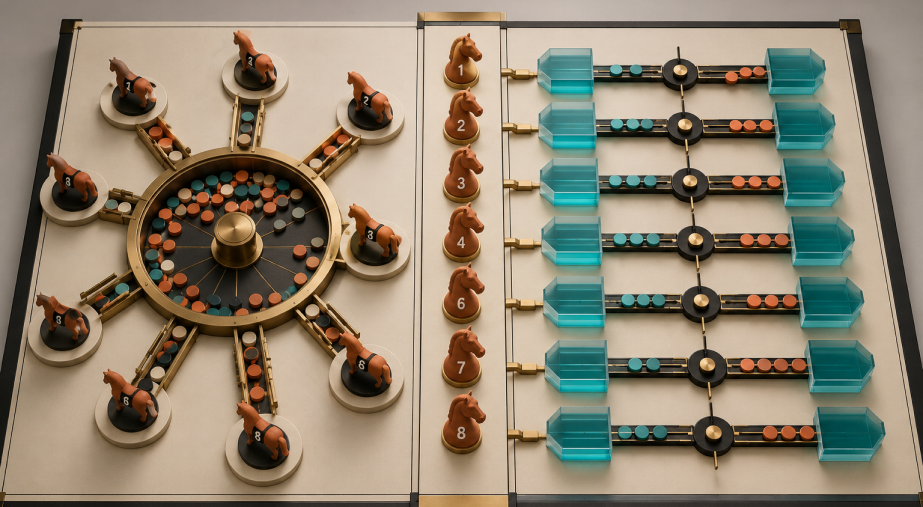
A market with $100,000 of participation divided between two football outcomes can develop considerable depth.
The same total interest fragmented among 12 horses creates a very different trading environment.
That matters because a visible probability becomes less informative when almost nobody is willing to trade around it.
A horse showing an implied probability of 10% in a thin market should not automatically be treated like a heavily traded contract with substantial orders on both sides.
Horse Racing Compresses Price Discovery Into Minutes
Timing creates another complication.
Some sports prediction contracts can accumulate liquidity for days.
Horse racing often concentrates meaningful price discovery immediately before post time.
A scratch can change the field.
Track conditions can shift.
Weather can alter expectations.
A jockey substitution may matter.
Late wagering can substantially change the pari-mutuel price.
Sophisticated racing participants may also wait until close to post time because they want more information about how the pools are developing.
An exchange would need to absorb those changes extremely quickly.
Imagine that a horse is trading around a relatively low probability on a prediction market while money suddenly pours into the established pari-mutuel pool.
The exchange would need to determine whether that movement contains meaningful information.
If participants react, the contract price could move rapidly.
If liquidity is too thin to react, the exchange could display a stale probability while the established racing market has already changed.
That is a difficult environment for a platform attempting to establish itself as a reliable source of price discovery.
Racing Integrity Adds Another Surveillance Layer
Horse racing also contains specialized integrity considerations.
Information about a horse’s condition, training, equipment or availability can become economically significant before a race.
That makes market surveillance especially important.
The CFTC has already made clear that nonpublic information can create enforcement issues in prediction markets. In February 2026, the agency issued a prediction-markets enforcement advisory after cases involving alleged fraud and misuse of nonpublic information on event-contract markets.
The advisory emphasized the CFTC’s authority to police illegal trading practices on designated contract markets.
Horse racing would add another layer to that problem.
Racing regulators already monitor wagering patterns and integrity issues. Prediction exchanges could create a second source of trading data around the same events.
An unusual price movement would therefore need context.
Did public information change?
Was there a scratch?
Did a horse’s pari-mutuel odds move simultaneously?
Was the contract simply thinly traded?
Or did someone trade before information became widely available?
None of those questions automatically indicates wrongdoing. They illustrate why racing surveillance becomes more complicated when multiple market structures exist around the same event.
Recent Racing Events Show Why Integrity Data Matters
The integrity issue is not theoretical.
Racing authorities are currently investigating unusual wagering activity connected with the so-called Fair Hill Five, a group of longshot horses whose performances on August 9 attracted attention after coordinated wagering was reported in Britain.
Horses associated with Maryland’s Fair Hill Training Center produced unexpected results at tracks including Saratoga and Monmouth Park.
HISA, the Horseracing Integrity and Welfare Unit and other racing organizations are examining the circumstances. No finding of race-fixing or other misconduct should be assumed from the investigation itself.
The episode nevertheless demonstrates how unusual wagering patterns can rapidly become an integrity issue in racing.
Adding another liquid market for the same horses would give investigators additional information—but also another system they would need to understand.
The Kentucky Derby May Actually Be the Easy Product
There is an irony in the prediction-market problem.
The Kentucky Derby may be one of the easiest horse races for an exchange to support economically.
Millions of Americans recognize it.
National media cover the field for weeks.
The race attracts enormous wagering volume.
Information is widely distributed.
A prediction exchange could reasonably expect substantial customer interest.
Everyday racing is much harder.
A platform trying to offer a full racing calendar would need to create meaningful liquidity repeatedly throughout the day across many tracks.
The problem becomes particularly severe when one race has a large field.
This makes racing fundamentally different from listing one Super Bowl contract that can accumulate activity for two weeks.
A routine race may receive most of its economically significant wagering activity during a short period immediately before the horses enter the starting gate.
Prediction markets would have little time to build depth and discover a stable price.
Prediction Markets Could Work With Racing Instead of Around It
The current conflict does not necessarily mean prediction markets can never become part of American horse racing.
Partnership may offer another route.
Prediction platforms could negotiate with tracks, racing associations or other rights holders rather than attempting to list contracts independently.
That would potentially address at least some of the industry’s concerns surrounding consent and economic participation.
Horse racing has adapted its wagering distribution before.
Simulcasting changed where people could watch and wager on races.
Advance-deposit wagering moved much of the experience online.
Mobile technology changed it again.
Prediction exchanges could theoretically become another distribution model.
But such a system would need to determine how exchange trading interacts with pari-mutuel wagering, how racing stakeholders participate economically, how integrity information is shared and how federal and state rules apply.
Those are not minor implementation questions.
They go to the core of how American racing funds itself.
Racing Is Testing the Limits of the Prediction-Market Model
Prediction markets have often expanded into sports through a straightforward idea: define a measurable outcome, create an event contract and allow participants to trade around the probability of that outcome.
Horse racing demonstrates why that formula cannot necessarily be applied everywhere.
The sport already has a federal statute specifically addressing interstate wagering.
It already has an established national wagering infrastructure.
Its pari-mutuel pools contribute to a broader racing economy.
Tracks and racing organizations claim consent rights that conventional professional sports teams generally do not possess in the same form.
Racing also presents difficult liquidity, timing and integrity challenges even if the legal issues can eventually be resolved.
The Kentucky Derby demonstrated the practical effect. Prediction platforms that have aggressively entered other sports did not force their way into America’s most famous horse race.
Saratoga has now brought the underlying regulatory debate back into focus.
That does not mean horse racing is permanently closed to prediction markets.
It means exchanges may have to approach racing differently.
Football and basketball have largely tested whether prediction markets can grow despite state regulatory opposition. Horse racing poses a deeper question: Can a prediction exchange enter an established wagering ecosystem without bypassing the laws, consent relationships and revenue structures that already support the sport?
So far, that remains one of the biggest sports-market problems prediction platforms have not cracked.