Prediction markets became one of the dominant regulatory subjects at the 2026 Global Gaming Expo in Las Vegas, but Nevada’s position on sports event contracts was already unusually clear before the industry’s largest annual gathering opened its doors.
G2E ran from September 28 through October 1, 2026, at The Venetian Expo in Las Vegas, bringing together more than 25,000 gaming professionals, more than 400 exhibitors and representatives from more than 120 countries and regions. While artificial intelligence, casino technology and responsible gaming occupied large parts of the agenda, prediction markets repeatedly returned to the center of discussions about sports betting regulation. The Global Gaming Expo positioned regulatory change among the issues shaping the industry’s next phase.
For readers focused on soccer and 1X2 markets, the dispute is more than an institutional fight between regulators and financial-market companies. Sports event contracts can offer exposure to many of the same underlying outcomes that appear at sportsbooks, including whether a team wins a match or whether a particular event occurs during play.
The central disagreement is over what those products legally are.
Prediction-market operators have argued that event contracts traded on federally regulated exchanges fall under the Commodity Futures Trading Commission framework. Nevada regulators argue that when those contracts are based on sports outcomes, they function as sports wagering and therefore must comply with Nevada gaming law.
Recent court decisions have made that divide sharper rather than simpler.
Nevada Has Built A Sustained Enforcement Campaign
Nevada’s opposition did not begin at G2E.
The Nevada Gaming Control Board sent Kalshi a cease-and-desist letter on March 4, 2025, asserting that sports event contracts offered to people in Nevada violated state gaming regulations. What followed developed into an extended series of federal and state court proceedings involving Kalshi and other prediction-market businesses.
According to the Gaming Control Board’s official prediction-market enforcement timeline, Nevada later took action involving Robinhood, Crypto.com, Polymarket and Coinbase as the state attempted to establish that sports-related event contracts could not simply operate outside its existing gaming framework.
The state obtained important results during 2026.
A Nevada state court granted a preliminary injunction against Kalshi on April 3, and the state reached an agreement during the summer requiring Kalshi to stop its sports prediction-market business in Nevada. Governor Joe Lombardo publicly backed the enforcement approach in July, arguing that gaming businesses operating in Nevada need to meet the state’s standards for oversight and enforcement.
The more consequential federal development came one month later.
On August 28, 2026, the U.S. Court of Appeals for the Ninth Circuit declined to shield Kalshi’s sports contracts from Nevada gaming regulation.
That ruling substantially strengthened Nevada’s legal position.
The Ninth Circuit Gave Nevada An Important Win
The Ninth Circuit case centered on whether the federal Commodity Exchange Act prevented Nevada from applying its gaming regulations to Kalshi’s sports event contracts.
Kalshi argued that it operates a designated contract market under the Commodity Exchange Act and that the Commodity Futures Trading Commission therefore has exclusive jurisdiction over the relevant products.
The Ninth Circuit was not persuaded.
In its August 28 decision, the court affirmed the dissolution of a preliminary injunction that had prevented Nevada from enforcing state law against Kalshi’s sports contracts. The court concluded that Kalshi had not demonstrated a likelihood that federal law preempted Nevada gaming regulation.
More specifically, the court determined at this stage of the litigation that Kalshi’s sports event contracts did not meet the statutory definition of swaps that would receive the federal preemption Kalshi was seeking.
The full Ninth Circuit Kalshi decision therefore represents an important state-level victory, but it should not be interpreted as a final nationwide resolution of every legal question surrounding prediction markets. The case concerned preliminary injunctive relief, and similar disputes have produced different outcomes elsewhere.
That distinction matters.
Prediction-market regulation is increasingly becoming a question of jurisdiction as much as product design.
The Sixth Circuit Added To The Pressure
Nevada is no longer alone in receiving strong federal appellate support for state regulation of sports event contracts.
On September 25, 2026, the U.S. Court of Appeals for the Sixth Circuit issued a decision involving challenges brought by Kalshi against regulators in Ohio and Tennessee.
The Sixth Circuit held that Kalshi had not shown that its sports event contracts satisfied the statutory definition of a swap for purposes of obtaining exclusive CFTC jurisdiction. The court also concluded that even if the contracts were treated as swaps for the analysis, the Commodity Exchange Act did not preempt the state gambling laws at issue.
The decision affirmed an Ohio federal court’s refusal to give Kalshi a preliminary injunction and vacated an injunction Kalshi had obtained in Tennessee.
The Sixth Circuit ruling is particularly notable because the court discussed products extending well beyond a basic game winner. Examples included sports-event outcomes, soccer corner-kick contracts and multi-event combinations.
For 1X2 market readers, that detail helps explain why traditional gaming regulators are paying close attention.
A contract asking whether a particular soccer club wins a match may use a different market structure from a fixed-odds sportsbook, but the underlying event being priced can be substantially similar.
That is where regulation and market mechanics begin to intersect.
The Courts Still Do Not Speak With One Voice
The developing legal picture is not completely one-sided.
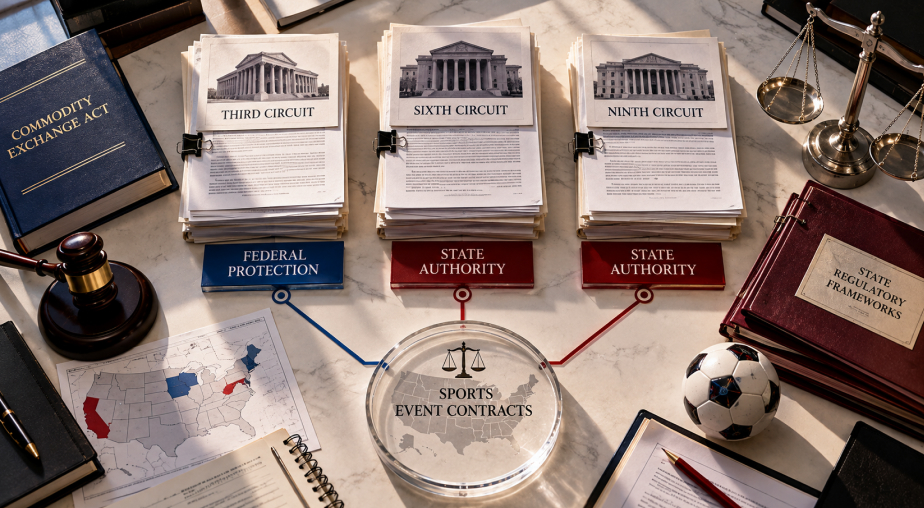
Earlier in 2026, the U.S. Court of Appeals for the Third Circuit reached a more favorable preliminary conclusion for Kalshi in litigation involving New Jersey.
On April 6, the Third Circuit upheld a preliminary injunction preventing New Jersey regulators from enforcing state law against Kalshi’s sports event contracts while the litigation continued. The court found that Kalshi had demonstrated a reasonable chance of succeeding on its argument that federal law preempted the relevant state restrictions.
The Third Circuit decision stands in clear tension with the later Ninth and Sixth Circuit decisions.
That creates a regulatory landscape in which geography can matter almost as much as product structure.
| Federal Appeals Court | State Dispute | 2026 Preliminary Direction |
|---|---|---|
| Third Circuit | New Jersey | More favorable to Kalshi’s federal-preemption argument |
| Ninth Circuit | Nevada | More favorable to state gaming regulation |
| Sixth Circuit | Ohio and Tennessee | More favorable to state gaming regulation |
These rulings should not be reduced to a simple national declaration that prediction markets are either universally legal or universally prohibited.
They arise from individual cases, procedural stages and specific state enforcement actions.
For market users, however, the practical implication is increasingly obvious: access risk has become part of prediction-market analysis.
That issue was already explored in 1×2 Betting Pro’s examination of prediction market pricing after the Ninth Circuit, where regulatory exposure became another variable alongside liquidity and price.
G2E Made The Industry Divide Public
The legal conflict moved directly onto the conference stage at G2E 2026.
During a session examining casino regulation, prediction markets, compliance and risk, Nevada Gaming Control Board Chairman Mike Dreitzer reiterated that companies engaging in activities Nevada considers gaming need to follow Nevada law.
The broader conference atmosphere was similarly confrontational.
American Gaming Association President and CEO Bill Miller, casino executives and regulatory representatives used the Las Vegas gathering to argue that sports prediction markets should not obtain a regulatory advantage over licensed sportsbooks simply because their products are structured as event contracts.
Coverage from G2E showed that the issue had moved well beyond an abstract debate about financial-market terminology. It now involves licensing, taxation, age restrictions, consumer protection, responsible gambling controls, tribal gaming interests and state sovereignty.
Prediction-market companies dispute the traditional gaming industry’s characterization.
Their model is generally built around participants buying and selling event contracts against other participants, with prices changing as supply, demand and information change. That differs structurally from a conventional sportsbook, where an operator posts prices and accepts wagers against its book.
The disagreement is therefore partly about whether differences in market architecture should produce differences in regulation.
A Soccer 1X2 Market Shows Why The Distinction Is Difficult
Soccer provides one of the clearest examples.
A conventional sportsbook can offer three pre-match prices:
1 represents the home team winning.
X represents a draw.
2 represents the away team winning.
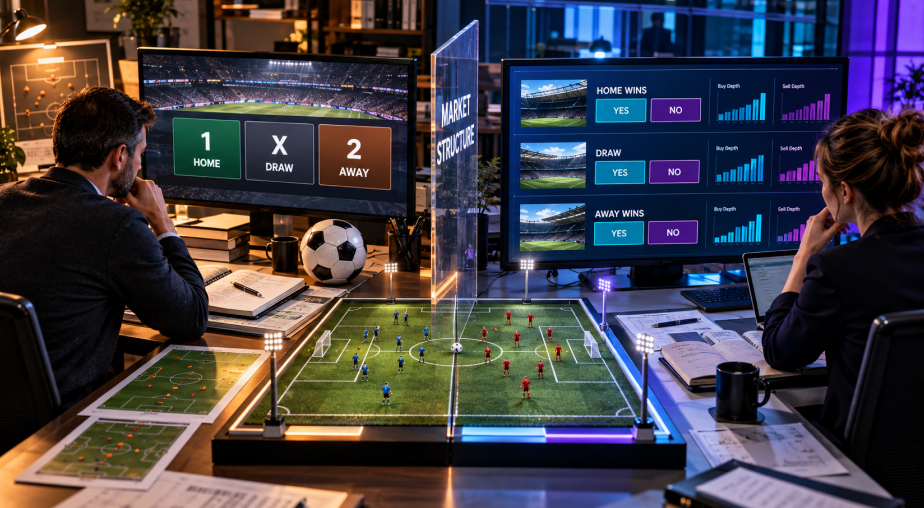
A prediction exchange can reach similar economic territory using separately traded event contracts. One contract could resolve based on whether the home team wins. Another could concern whether the match ends level. Contract values can move as participants buy and sell.
The mechanisms are different.
The underlying uncertainty is not.
This creates several important distinctions for people comparing sports markets.
A sportsbook’s quoted odds incorporate an operator margin. A prediction market’s displayed contract prices emerge from available buy and sell orders and may be affected by liquidity, spread and trading fees.
A sportsbook wager generally remains a fixed position after placement unless cash-out or exchange features are available. A prediction-market position may be tradable before final settlement.
Most importantly, however, regulatory availability can differ even when both products reference the same soccer match.
That is why comparing only the apparent probability or price can be incomplete.
A seemingly attractive contract may have different settlement rules, fee structures, liquidity conditions and jurisdictional restrictions from a sportsbook market. Regulatory changes can also alter whether a market remains available in a particular state.
Nevada Is Testing The Limits Of Federal Market Expansion
Nevada occupies an unusual position in this fight.
It is both America’s most established gaming jurisdiction and a state with a powerful incentive to defend an extensive licensing and regulatory system built over decades.
The state’s argument is therefore broader than whether one company should be allowed to offer one type of sports contract.
Nevada’s regulators are effectively asking whether a federally registered prediction exchange can offer a product based on a sporting event without satisfying the same state-level obligations that apply to licensed sportsbooks operating on that event.
Prediction-market operators approach the question from the other direction: if Congress created a federal framework for designated contract markets and the CFTC oversees those markets, how far can individual states reach into contracts traded on them?
The courts are now working through that boundary.
For the sports-betting market, that uncertainty affects more than compliance departments. It could influence where sports products are available, which companies can compete for volume, what protections apply to users and how efficiently prices develop across competing platforms.
Regulation Is Becoming Part Of Price Comparison
The rapid growth of prediction markets has created another venue for sports price discovery, but regulatory fragmentation means bettors and traders cannot treat every displayed sports price as interchangeable.
Traditional sportsbooks, betting exchanges and prediction markets can all express an expectation about the same event while operating under substantially different legal, commercial and liquidity structures.
Nevada’s approach emphasizes that distinction.
Following the Ninth Circuit ruling and the state’s sustained enforcement campaign, sports prediction contracts face a considerably less welcoming environment in Nevada than in jurisdictions where federal courts have temporarily protected Kalshi from state action.
The Sixth Circuit’s September ruling widened the importance of that debate by supporting state regulatory authority in disputes involving Ohio and Tennessee as well.
None of those decisions guarantees the final national outcome.
But the trend is enough to change how sports markets should be evaluated.
For someone comparing soccer 1X2 prices, the relevant questions now extend beyond whether 1, X or 2 appears cheaper on one platform.
Market depth matters. Fees matter. Settlement terms matter. Operator structure matters.
And increasingly, jurisdiction matters too.