
One number has become central to the growing regulatory dispute between U.S. sportsbooks and prediction markets: $5.1 billion.
The American Gaming Association estimates that users between the ages of 18 and 20 generated approximately $5.1 billion in sports-contract trading volume on Kalshi as of September 1, 2026.
That age group occupies an unusual position in the rapidly changing U.S. sports-wagering market.
Kalshi allows individuals to open accounts from age 18. Conventional regulated sportsbooks, by contrast, require customers to be at least 21 in most U.S. jurisdictions where sports betting is legal.
The difference means an 18-, 19- or 20-year-old who cannot legally open a sportsbook account in many states may nevertheless meet Kalshi’s age requirement to trade federally regulated event contracts.
That distinction has become one of the most consequential consumer-protection questions surrounding prediction markets.
But the headline figure requires context.
The $5.1 billion number comes from an American Gaming Association estimate, and the association represents the regulated gaming industry. Its public release does not provide a detailed methodology showing how the age-specific Kalshi volume was calculated.
It should therefore be treated as an industry estimate rather than independently verified Kalshi account data.
Even with that limitation, the underlying age-policy difference is real—and increasingly important as sports become the dominant source of prediction-market activity.
The AGA Estimates $5.1 Billion From Ages 18–20
The American Gaming Association highlighted the age issue while releasing its NFL wagering outlook in early September.
The association said sports contracts account for approximately 80% of Kalshi’s volume and estimated that users ages 18–20 had generated approximately $5.1 billion in volume.
The AGA also said those customers fall below the minimum sportsbook age in 35 of the 40 U.S. jurisdictions where sports betting is legal.
That immediately made the figure part of the wider regulatory fight over sports event contracts.
The association’s argument is straightforward: customers who would be too young to use most regulated sportsbooks can participate in sports-related prediction markets because the platforms operate under a different regulatory framework.
The AGA has used that distinction to argue that prediction markets offering sports contracts should not be treated differently from sports betting.
Prediction-market operators dispute that premise and characterize their products as federally regulated event contracts rather than state-regulated wagers.
Those competing definitions are at the center of several ongoing legal disputes.
The $5.1 Billion Figure Is an Estimate, Not an Audited Age Breakdown
There is an important limitation.
The American Gaming Association’s NFL market statement identifies approximately $5.1 billion in Kalshi volume associated with people between 18 and 20.
However, the publicly available statement does not explain the methodology behind that estimate in detail.
It does not provide an audited table of Kalshi accounts by age.
Nor does it explain exactly how individual trading activity was attributed to the age cohort.
That matters because the AGA is not a neutral statistical agency in this dispute.
It represents commercial and tribal gaming interests and has taken a clear position against sports event contracts being offered outside traditional state and tribal gaming frameworks.
The age gap itself can be verified independently.
The exact $5.1 billion figure should still be described accurately as an AGA estimate.
Kalshi Allows Accounts From Age 18
Kalshi’s own eligibility rules establish the central regulatory difference.
According to Kalshi’s account eligibility requirements, an individual must be 18 or older to open an account.
The company can require identity-document verification and says it collects customer information to comply with applicable U.S. laws and Commodity Futures Trading Commission regulations.
Kalshi describes its products as financial derivatives based on events.
That classification is crucial.
The platform operates as a federally regulated designated contract market rather than as a state-licensed sportsbook.
Traditional sportsbooks operate under state or tribal gaming laws.
Those two systems produce different requirements.
Age is one of the clearest examples.
Most Sportsbooks Use a 21-Year Minimum
For conventional sports betting, 21 has become the dominant minimum age across the United States.
There are exceptions.
But according to the AGA, 35 of the 40 jurisdictions with legal sports wagering use an age threshold above the 18–20 cohort highlighted in its estimate.
That creates an unusual regulatory boundary.
A 20-year-old may be legally prohibited from placing a conventional sports wager through a sportsbook in a particular jurisdiction while still meeting the age requirement for an event-contract exchange.
The difference exists because the two products are governed through different regulatory systems.
It is not simply a case of one operator choosing a younger customer base than another.
Sports Have Made the Age Difference More Important
The distinction would attract less attention if prediction exchanges primarily offered economic indicators, elections and weather contracts.
That is no longer the market.
Sports have become one of the primary engines of prediction-market growth.
The AGA estimates that sports account for approximately 80% of Kalshi’s volume.
The beginning of the 2026 NFL season demonstrated the scale.
Prediction markets generated at least $5.83 billion in reported trading volume during the opening NFL weekend, according to Aldrin Research figures reported by Barron’s.
Kalshi accounted for approximately $4.89 billion of that activity.
Those figures are not directly comparable with sportsbook handle because event contracts can change hands multiple times and prediction exchanges report trading activity differently.
Nevertheless, they demonstrate that sports event contracts are no longer a small product category.
The NFL Makes the Consumer-Protection Question More Visible
Football intensifies the issue because of its reach among younger adults.
Prediction exchanges now offer markets covering game winners, totals, player outcomes and multi-event combinations.
That increasingly resembles the menu customers encounter at conventional sportsbooks, even though the underlying market structure and regulatory classification differ.
From the consumer’s perspective, the distinction can become difficult to understand.
One application may describe an outcome as a wager.
Another may present a Yes/No event contract.
Both can involve putting money at risk based on what happens during the same NFL game.
That is why age requirements have become more politically significant as prediction-market sports offerings expand.
The $5.1 Billion Is Trading Volume, Not Customer Losses
Another distinction is essential.
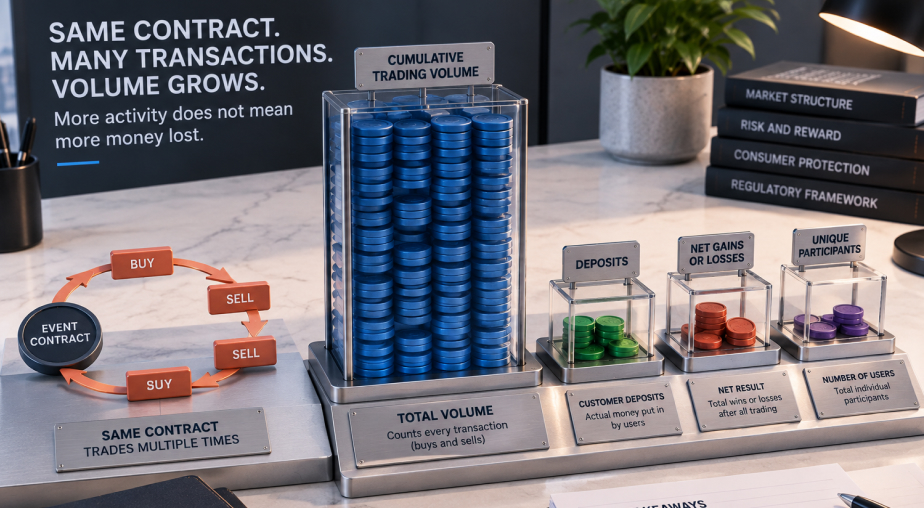
The AGA’s $5.1 billion figure refers to estimated volume.
It does not mean 18- to 20-year-olds lost $5.1 billion.
It also does not necessarily mean they deposited $5.1 billion.
Prediction-market contracts are tradable.
A participant can purchase a position and later sell it.
The same underlying contract can therefore contribute to trading volume multiple times before settlement.
That differs from conventional sportsbook handle.
If a sportsbook customer places a $100 wager, that transaction generally contributes $100 to sportsbook handle.
Exchange-style markets can generate repeated transactions around the same event.
Any comparison between the $5.1 billion estimate and conventional sportsbook wagering must account for that structural difference.
It Also Does Not Tell Us How Many Young Adults Participated
The headline figure does not reveal another important number: the number of individual customers responsible for the estimated volume.
Five billion dollars spread across a very large number of users would describe a different market from the same volume concentrated among a much smaller number of highly active traders.
Publicly available AGA material does not provide enough information to determine that distribution.
Volume alone therefore cannot establish typical behavior among 18- to 20-year-old Kalshi users.
Nor does it show average deposits, losses, profits, trading frequency or sports-market exposure for an individual customer.
Those distinctions matter when discussing consumer risk.
Trading Volume Can Be Concentrated Among Active Users
Exchange markets can naturally produce high activity from relatively active participants.
A trader may enter a position, adjust exposure, exit it and later trade another contract tied to the same sporting event.
Multi-leg products can create still more activity.
This means aggregate trading volume can rise quickly without requiring an equivalent increase in unique users.
That does not make the volume unimportant.
It means policymakers need more granular information if they want to understand how younger customers are actually using these products.
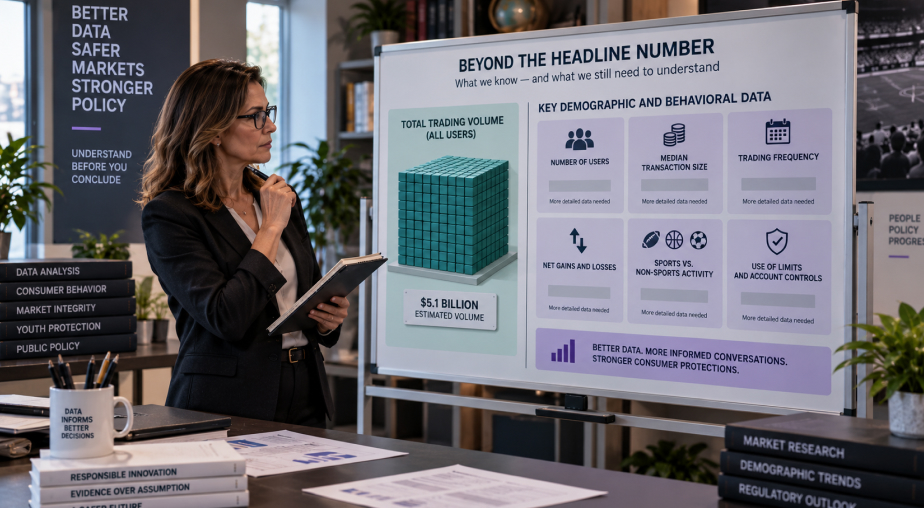
Useful data would include the number of accounts in each age cohort, median transaction size, trading frequency, net gains and losses, and the proportion of activity involving sports.
Without those details, the $5.1 billion estimate is best understood as a signal of scale rather than a complete picture of consumer behavior.
The Debate Is Really About Regulatory Classification
The age question exposes the deeper disagreement surrounding prediction markets.
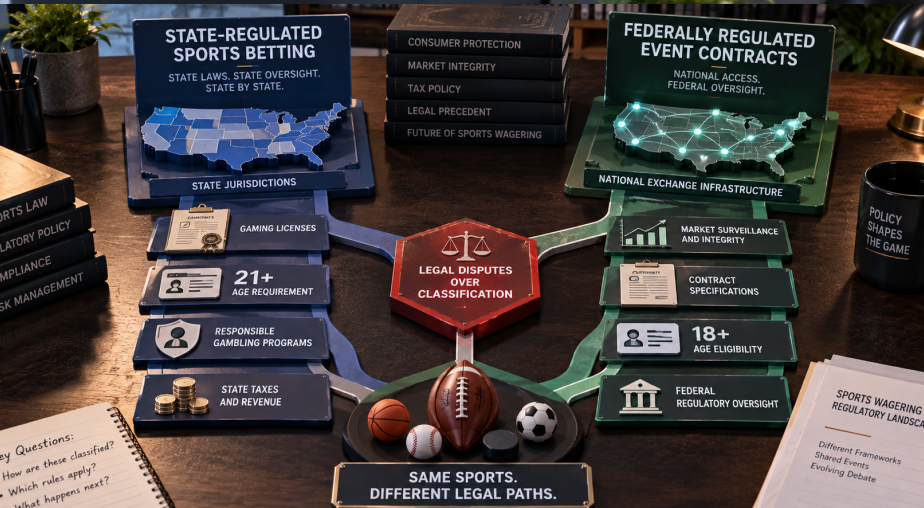
State gaming regulators and the conventional sportsbook industry generally view sports event contracts as functionally similar to sports betting.
Prediction exchanges argue that they operate regulated derivatives markets under federal commodities law.
If sports contracts are treated primarily as derivatives, the regulatory structure surrounding exchanges becomes central.
If they are treated primarily as gambling, state and tribal gaming laws become much more important.
That distinction affects more than age.
It influences licensing, taxation, advertising, responsible-gambling requirements, product approval and geographic availability.
CFTC Regulation Does Not Mirror Sportsbook Regulation
Kalshi is subject to federal oversight through the Commodity Futures Trading Commission.
That does not mean its regulatory structure is identical to that of a sportsbook.
A sportsbook typically answers to a state gaming regulator with gambling-specific rules.
Those rules can cover advertising, self-exclusion, responsible-gambling messaging, account restrictions, dispute procedures and permitted wager types.
A designated contract market operates under commodities regulation.
Its requirements focus on exchange integrity, contract rules, market surveillance, financial controls and other obligations associated with derivatives markets.
Both are regulated systems.
They are simply designed around different regulatory purposes.
Sports event contracts have forced those systems into direct contact.
The Products Are Becoming Harder for Consumers to Distinguish
That regulatory distinction can be much clearer to lawyers than to customers.
Imagine two screens involving the same football game.
A sportsbook displays prices on which team will win.
A prediction exchange offers Yes and No contracts on the same outcome.
The financial mechanics differ.
The terminology differs.
Settlement structures and fees can differ.
But from a casual customer’s perspective, both involve risking money on the result of a sporting event.
That creates a disclosure challenge.
Platforms need to make clear what product the customer is using, how pricing works, what fees apply and what protections are available.
The issue becomes particularly important for younger adults who may encounter prediction markets before becoming eligible for conventional sportsbooks in their jurisdiction.
The AGA Has Made Age a Central Part of Its Case
The American Gaming Association has repeatedly emphasized younger customers while campaigning against sports prediction markets.
AGA President and CEO Bill Miller argues that prediction-market companies blur the distinction between sports wagering and investment products.
The association also claims prediction markets have reduced potential state gaming-tax revenue and operate outside gambling-specific protections established by state and tribal regulators.
These are advocacy positions from an industry trade group and should be understood as such.
Prediction-market companies reject the idea that they are simply unlicensed sportsbooks.
The dispute therefore cannot be resolved by adopting either industry’s terminology as fact.
What can be established is that their regulatory requirements differ significantly—and age eligibility is among the clearest differences.
The Age Issue Is Becoming Part of Court Battles
The disagreement is increasingly reaching federal courts.
One important case involves Blue Lake Rancheria and Chicken Ranch Rancheria of Me-Wuk Indians in California.
On September 16, 2026, the U.S. Court of Appeals for the Ninth Circuit revived significant portions of their lawsuit involving Kalshi’s sports event contracts on tribal lands.
The ruling did not create an immediate nationwide ban on Kalshi.
It did, however, reinforce the unresolved tension between federally regulated event contracts and gambling authority exercised through states and tribal governments.
Age restrictions are one part of the broader policy dispute.
The larger question is which regulatory framework should control sports-related products that economically resemble wagers but are structured as exchange-traded contracts.
Prediction Markets Reach Places Sportsbooks Cannot
Geography adds another layer.
Conventional online sports betting remains unavailable in several large U.S. states.
Prediction exchanges have operated under a federal framework that can provide broader geographic reach, although litigation and state enforcement efforts continue to challenge that model.
This means some 18- to 20-year-old customers may live in places where they would be unable to access a legal sportsbook regardless of age.
California and Texas are especially significant because of their enormous populations and lack of statewide regulated online sports betting.
Prediction-market activity in those states has become an important part of the industry’s growth story.
That makes the debate about more than age.
It is also about geographic access.
Younger Users Highlight the Difference Between Trading and Betting
The terminology used by each industry matters.
Prediction markets frequently use words such as:
- contracts,
- trading,
- probabilities,
- positions,
- markets.
Sportsbooks use terms such as:
- wagers,
- odds,
- bets,
- parlays,
- payouts.
Those vocabulary differences reflect genuine differences in market mechanics.
But when both products are tied to the outcome of the same football or basketball game, terminology alone may not communicate the practical risk clearly enough.
A contract can lose value.
A wager can lose.
In both cases, the customer’s capital is at risk.
Clear disclosures become particularly important when products are marketed to adults who may have little experience with either derivatives markets or gambling.
Pricing Also Works Differently
Prediction exchanges typically express prices through contracts that settle at a fixed amount if an outcome occurs.
A contract trading near 60 cents can broadly communicate a market-implied probability around 60%, although fees, spreads and other mechanics affect the customer’s actual economics.
Sportsbooks incorporate operator margin into conventional odds.
That distinction is important for understanding value.
Our previous analysis of sportsbook pricing for favorites and underdogs explains how implied probability and bookmaker margin interact in traditional markets.
Prediction exchanges introduce another layer because customers may trade against other participants while market makers provide liquidity.
Neither structure eliminates risk.
Market Makers Add Another Consumer-Education Challenge
The AGA has also emphasized that prediction-market customers may trade against sophisticated professional participants.
That is not unusual for an exchange.
Financial markets routinely contain retail traders, institutional participants and market makers.
Professional liquidity can actually improve a market by narrowing spreads and making transactions easier to execute.
But it creates an information asymmetry worth understanding.
An inexperienced customer may be interacting with a market whose prices are influenced by professional quantitative firms.
That does not automatically make the market unfair.
It does mean the product should not be interpreted as a casual peer-to-peer game in which every participant has comparable resources or sophistication.
The $5.1 Billion Estimate Is Already Increasing
The scale may also be changing quickly.
Reporting on September 8 cited an updated American Gaming Association tracker estimating approximately $5.26 billion in year-to-date sports volume from Kalshi users ages 18–20, including roughly $128 million during the preceding week.
That increase illustrates why the age issue is receiving attention during football season.
NFL and college football schedules create a large number of recurring markets.
If younger-adult participation remains substantial throughout the season, the cumulative total could continue increasing rapidly.
Again, those numbers represent estimated trading volume rather than customer losses.
That distinction should remain explicit whenever the figures are discussed.
Sportsbooks and Prediction Markets Face Different Responsibilities
The debate should not be reduced to whether 18 or 21 is universally the “correct” age.
The more important policy question is whether similar sports-related financial risks should operate under different consumer-protection standards simply because their legal structures differ.
State gaming regulators have built one system.
Federal commodities regulators oversee another.
Prediction markets have created an overlap that lawmakers and courts did not previously have to address at this scale.
Age eligibility makes that overlap unusually visible.
A person can be legally old enough for one sports-outcome product while being too young for another product based on essentially the same game.
Better Data Would Improve the Debate
The AGA’s $5.1 billion estimate has generated a powerful headline.
More transparent data would make it substantially more useful.
Knowing total trading volume is only the beginning.
Policymakers would benefit from understanding:
- how many 18- to 20-year-old customers generated the volume,
- how concentrated the activity is among highly active traders,
- average and median position sizes,
- net gains and losses,
- frequency of sports trading,
- participation in multi-event combinations,
- use of account controls and trading limits.
Those metrics would provide a much stronger basis for evaluating actual consumer risk.
Without them, aggregate volume can demonstrate scale but not individual behavior.
The Age Gap Could Become a Defining Prediction-Market Issue
Prediction markets have already forced U.S. sports wagering to confront questions about federal versus state authority, exchange volume versus sportsbook handle, market making, taxation and geographic access.
Age may become just as important.
Kalshi’s published account rules permit participation from age 18.
Most regulated sportsbook jurisdictions set the threshold at 21.
And the American Gaming Association estimates that customers occupying the three-year gap between those limits have already generated billions of dollars in sports-contract volume.
The exact $5.1 billion estimate should be treated cautiously because the AGA has not publicly detailed its calculation methodology.
The regulatory difference behind it requires far less interpretation.
As sports event contracts become larger, more sophisticated and more closely integrated with football, basketball, baseball, hockey and soccer, policymakers will increasingly have to decide whether an 18-year minimum remains appropriate for products tied directly to sporting outcomes.
That debate will affect prediction exchanges, sportsbooks and regulators.
Most importantly, it will determine what protections apply to the youngest adults participating in America’s rapidly converging sports-market ecosystem.